

For three years …
AI stocks were bulletproof.
Every company tied to the buildout made money.
If you sold compute, built datacenters, or even whispered the letters “AI” - your stock went up.
CoreWeave (CRWV) rode that wave harder than anyone.
Backed by Nvidia and OpenAI, the company went public in 2025 looking unstoppable.
But cracks are forming beneath the surface.
Off-balance sheet deals.
Favorable terms for everyone except CoreWeave shareholders.
And a financial structure so aggressive it makes Wall Street veterans nervous.
Today we’ll cover what most investors don’t understand about CoreWeave.
The Neocloud Gamble
CoreWeave belongs to a new breed of cloud providers the industry calls “Neoclouds.”
Put simply, if you’re not Amazon, Google, or Microsoft - you’re a Neocloud.
The difference is simple.
The big three have cash-printing businesses funding their datacenter expansion.
Neoclouds don’t.
They have to borrow, raise capital, and scramble for every dollar needed to build multi-billion dollar facilities.
And right now, demand for datacenter capacity is so insane that anyone with GPUs to rent will find customers.
The problem?
Building and operating these facilities still requires staggering amounts of money.
Especially when you’re filling them with Nvidia GPUs carrying 75% profit margins.
Nvidia saw this problem early and became a lead investor in CoreWeave.
Some call it “circular financing” - Nvidia funding the companies buying Nvidia chips.
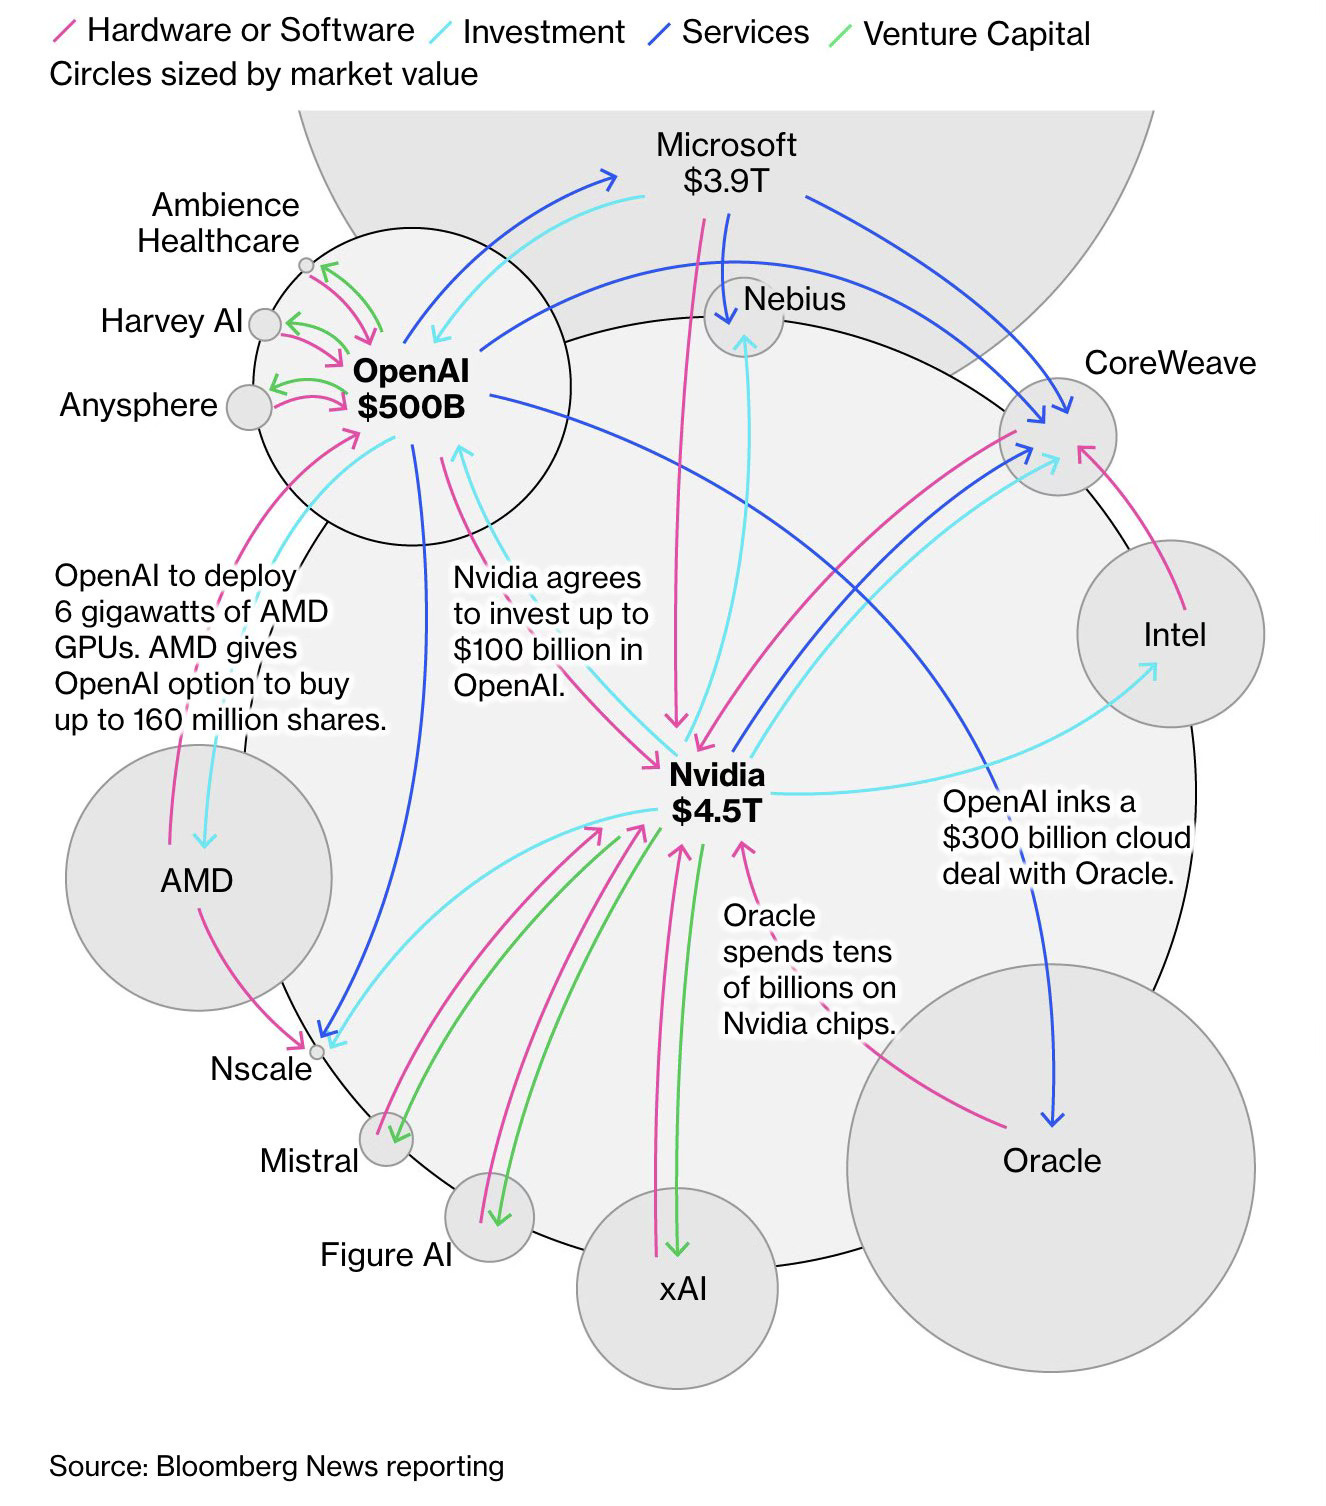
But circular financing isn’t new. Boeing does it. Ford does it. It’s how expensive manufacturing gets scaled.
CoreWeave just took it to the extreme.
With exclusive access to the world’s biggest GPU supplier and demand off the charts, CoreWeave did something even more bold (and risky).
They used their GPUs as collateral to get loans... to buy more GPUs.
That’s right - borrowing against the chips to buy more chips.
It shows up on the company’s financials in the form of interest expense.
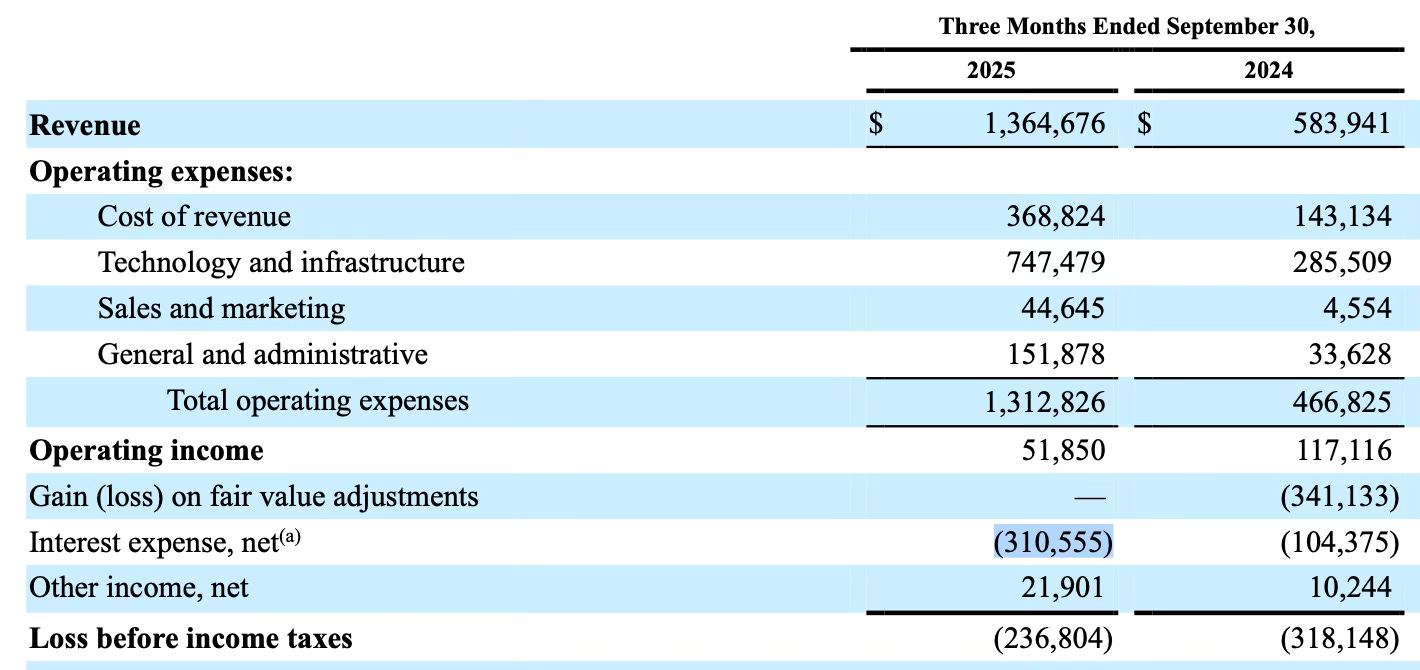
In a single quarter reported last week … $310M of interest expense!
But what most investors don’t realize is that’s not the full story.
That’s because CoreWeave has a significant “off balance sheet” arrangements.
Including a huge one with OpenAI.
The OpenAI Deal That Wasn’t What It Seemed
In March 2025, CoreWeave made headlines.
They announced an $11.9 billion deal with OpenAI. Later extended to over $22 billion through 2030.
Wall Street ate it up.
Investors celebrated.
The stock popped.
But nobody read the fine print.
This wasn’t a simple datacenter contract. It was financial engineering wrapped in a press release.
Here’s what actually happened.
The Special Purpose Vehicle Trick
CoreWeave didn’t put the OpenAI infrastructure on their own balance sheet.
Instead, they created something called a Special Purpose Vehicle - an SPV.
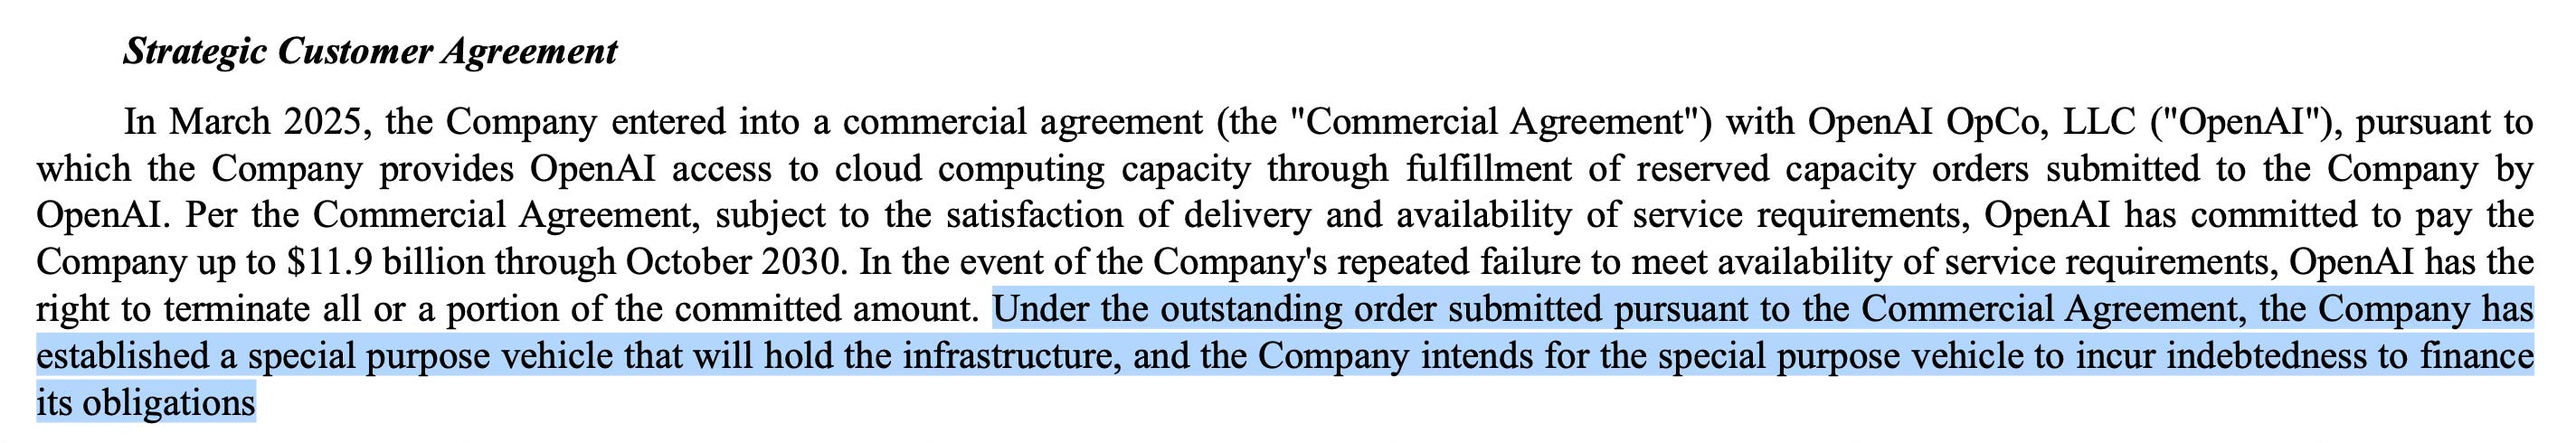
Think of it as a separate company that exists just for this one deal.
The SPV owns the GPUs.
The SPV owns the datacenter assets.
And most importantly - the SPV borrows the money to buy everything.
Not CoreWeave.
This means billions in debt stays off CoreWeave’s main financial statements.
Their balance sheet looks clean(er).
It’s the same playbook CoreWeave have been running.
Use GPUs as collateral, point to big customer commitments, and borrow against future revenue.
CoreWeave just took it a step further with the SPV structure.
OpenAI Isn’t Just a Customer
Here’s where it gets wild.
If CoreWeave fails to deliver - if they can’t meet uptime requirements or default on obligations - OpenAI doesn’t just cancel the contract.
They take over the entire operation.
OpenAI has a lien on the SPV’s equity.
That’s legal speak for “we own this if you screw up.”
OpenAI can foreclose on the infrastructure. Seize the GPUs. Walk away with the whole datacenter.
This isn’t a customer relationship. It’s a secured loan with OpenAI as the lender.
The $350 Million Sweetener Nobody Noticed
But wait - it gets better.
To lock in OpenAI, CoreWeave gave OpenAI $350 million worth of stock.
That’s right. CoreWeave paid OpenAI $350 million in equity just to sign the deal.
8.75 million shares at IPO price.
CoreWeave even books it as a “customer acquisition cost” on their balance sheet.
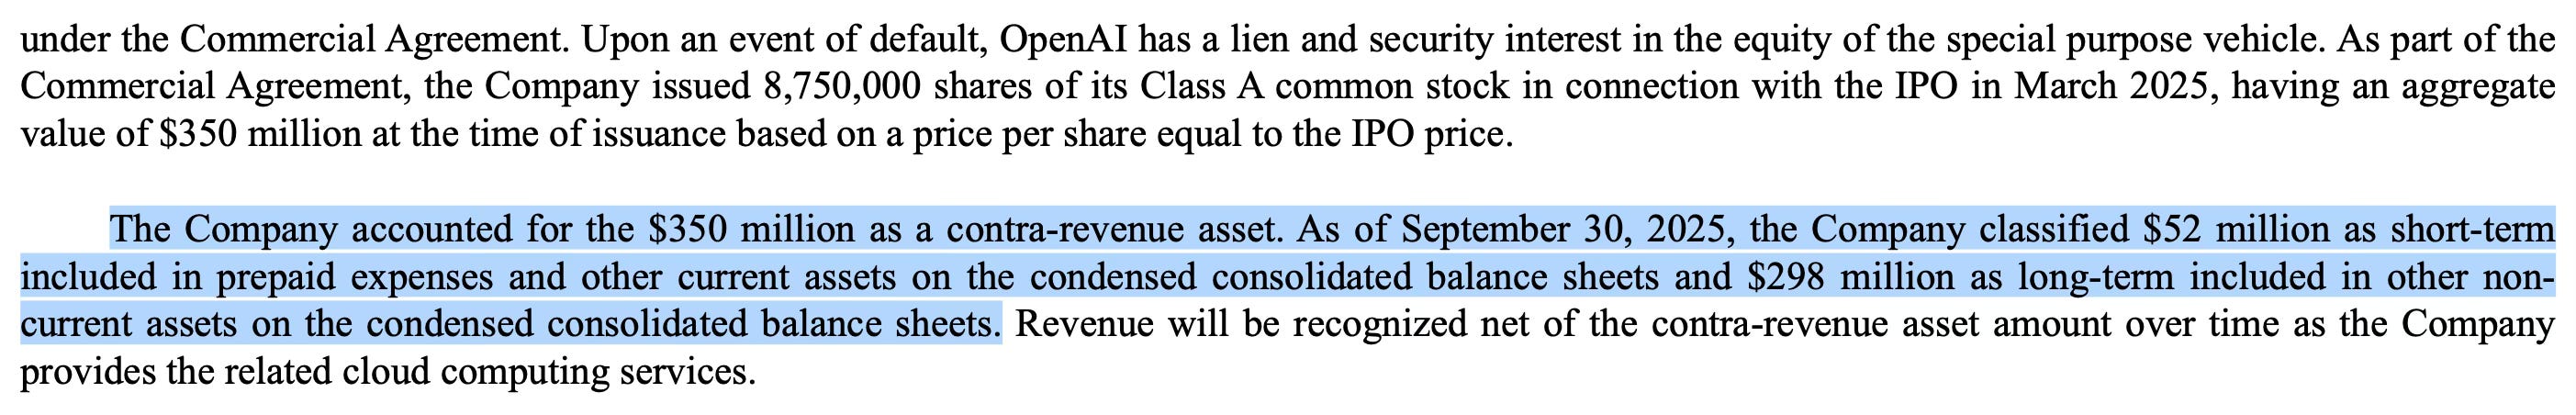
They’re treating it as contra-revenue - which means they’ll reduce future revenue from OpenAI until that $350 million is paid back through discounts.
Think of it the same way AT&T gives away free iPhones to lock you into a 5-year contract.
Except the “free phone” costs $350 million.
Why Give Away $350 Million?
Three reasons.
First - CoreWeave needed another major client besides Microsoft. Over 70% of their revenue came from one customer going into the IPO.
That’s a red flag investors couldn’t ignore.
Landing OpenAI let CoreWeave say “we have two mega-clients now” and calm nervous investors.
Second - it justified raising billions more in debt. With OpenAI locked in, lenders felt safer. Vendors offered better financing terms. The money machine kept running.
Third - the $22+ billion commitment became a story. A narrative. Proof that CoreWeave was a real player.
Never mind the conditional terms. Never mind the equity giveaway. Never mind the debt hidden in an SPV.
The headline number was all that mattered.
The Real Structure
Strip away the press release, and here’s what you have:
A company borrowing billions through an off-balance-sheet vehicle, giving a customer $350 million in stock and foreclosure rights, all to secure a contract with strict performance requirements that can be terminated if things go wrong.
This isn’t a partnership.
It’s financial engineering designed to keep the machine running while keeping the debt invisible.
And Wall Street bought it … until now.
When Reality Hit CoreWeave
In November 2025, CoreWeave reported Q3 earnings.
Revenue beat expectations. The backlog hit $55.6 billion - up 271% from the previous year (!!!!!!)
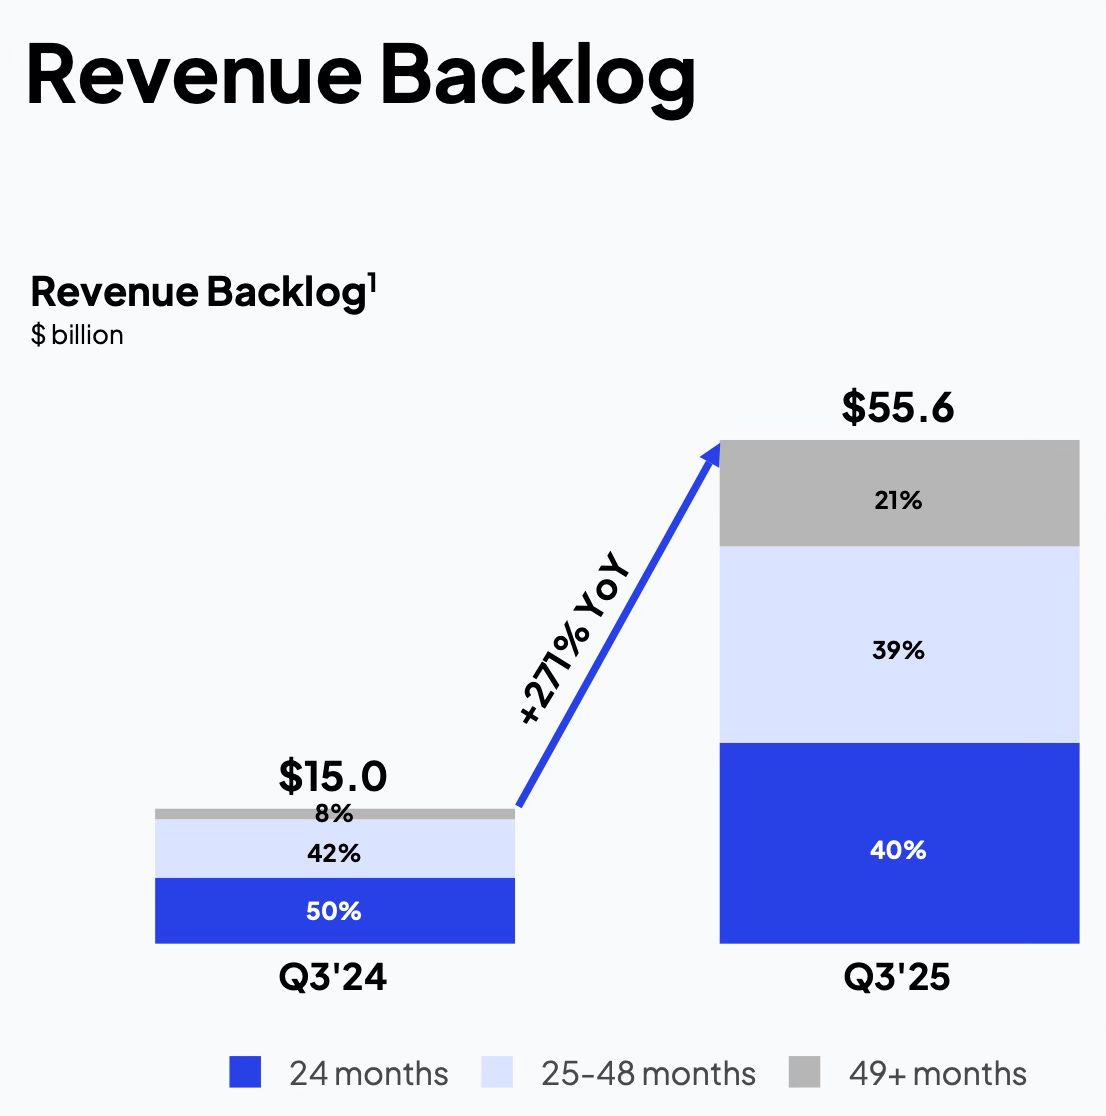
Wall Street should have celebrated.
Instead, shares cratered 16% in a single day.
The reason? A datacenter delay that revealed the house of cards underneath.
The Delay Nobody Saw Coming
CoreWeave’s problem was simple on the surface.
A third-party datacenter developer fell behind schedule delivering “powered shell” capacity - basically the physical buildings ready to fill with GPUs.
CoreWeave CEO Michael Intrator called it “temporary.” Blamed supply chain pressures.
He said demand for AI infrastructure materials and labor was unprecedented.
But he wouldn’t name which developer caused the problem.
Industry insiders suspect Core Scientific (CORZ) - a former crypto miner turned AI datacenter operator and CoreWeave partner.
When pressed by analysts on the conference call, Intrator dodged.
Said CoreWeave teams were on-site daily with contractors but refused to give specifics.
You can’t evade questions when you’re levered to the eyeballs like CoreWeave is.
The Real Damage
The delay shifted $200-300 million in Q4 revenue into Q1 2026.
But here’s the problem that spooked Wall Street.
Those GPUs CoreWeave already bought?
They’re sitting idle. Not generating revenue.
But the debt used to buy them?
Still accruing interest.
Remember - CoreWeave borrowed billions using those GPUs as collateral.
Interest expenses hit $311 million in Q3 alone. Triple what they paid a year earlier.
Every day those chips sit in an unfinished datacenter, CoreWeave bleeds money.
The OpenAI Problem
Now circle back to the OpenAI deal.
CoreWeave promised strict uptime requirements. Miss those targets repeatedly, and OpenAI can terminate the contract.
Or worse - foreclose on the entire SPV and seize the infrastructure.
What happens if the datacenter delays continue into Q1 2026? Or Q2?
CoreWeave insists the “overwhelming majority” of delays will resolve by Q1.
They’re also building their own datacenters in Pennsylvania to reduce reliance on third parties.
But the damage is done.
The market saw the chink in the armor.
Why This Matters More Than CoreWeave Admits
Shares fell 60% from their 52-week highs following the earnings report.
Some investors see it as a buying opportunity. Point to the massive backlog. Note that revenue is projected to grow 127% in 2026.
But they’re missing the bigger picture.
CoreWeave’s entire business model relies on perfect execution.
Borrow billions. Buy GPUs. Get datacenters online fast. Generate revenue immediately to service the debt.
Any delay in that chain breaks the machine.
And this delay proved something critical - CoreWeave doesn’t control their own destiny.
They’re dependent on third-party developers who can’t keep up with demand.
They’re dependent on customers like OpenAI not pulling the plug when uptime suffers.
They’re dependent on lenders staying patient while GPUs sit idle and interest piles up.
The Q3 delay wasn’t just a “temporary hiccup.”
It was proof that the financial engineering only works when everything goes perfectly.
And in the real world, nothing ever does.
Here’s where it gets scary for the investor that has been buying on the headlines.
Wall Street is now pricing in a 40% chance CoreWeave defaults in the next 5 years.
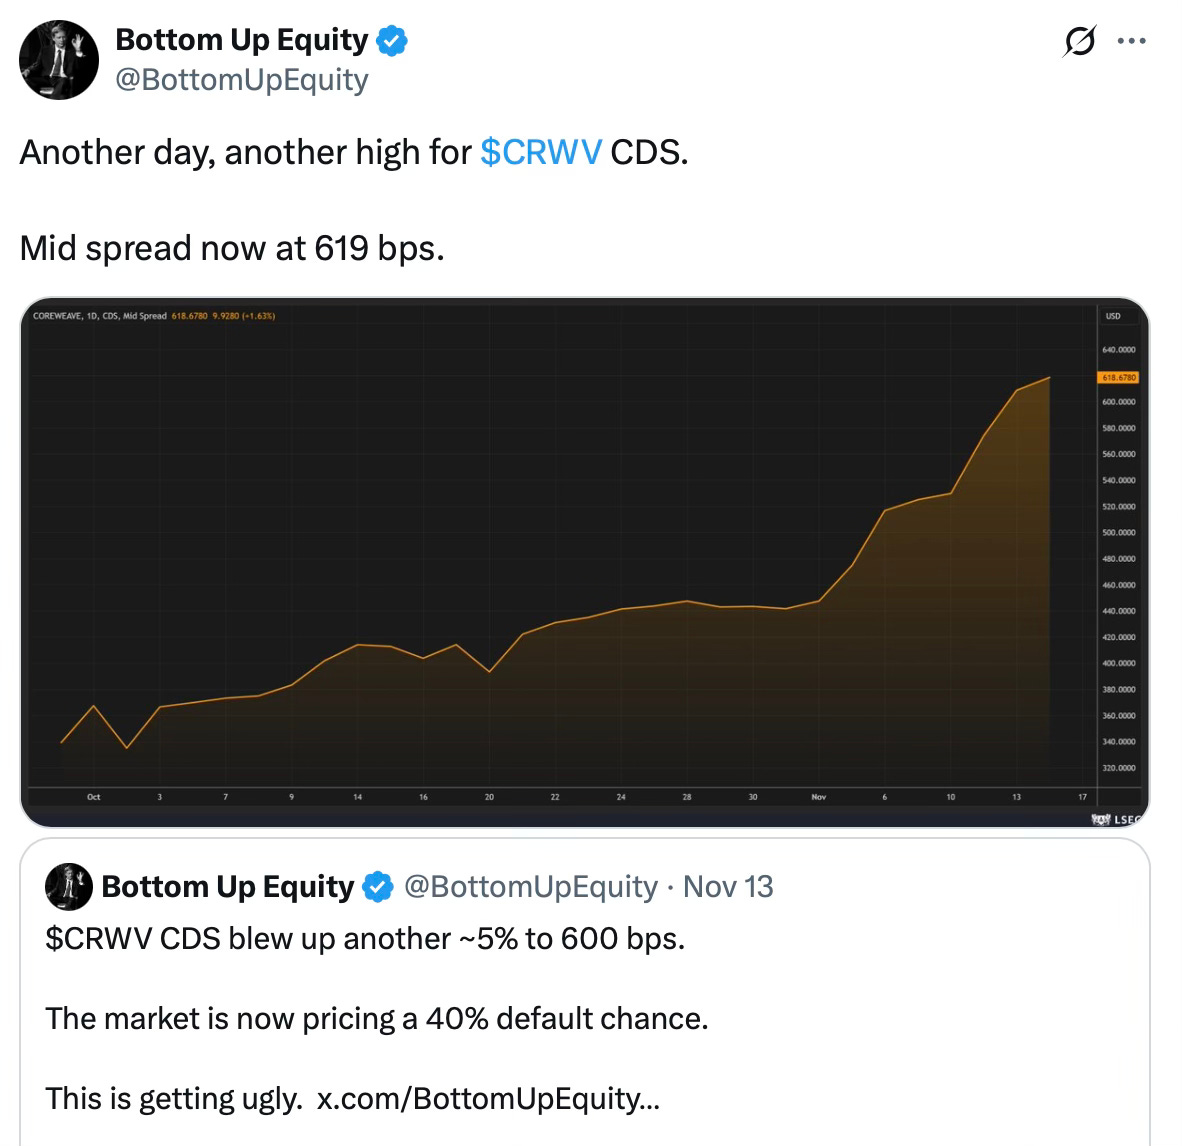
CDS = Credit Default Swaps
There’s a large crowd of investors that are buying stocks like CoreWeave because of the headlines.
Someone on YouTube says its a good investment …
Says “do your own research” …
But that person doesn’t even know where to find CoreWeave’s 10-Q, let alone understand the Special Purpose Vehicle terms or what CoreWeave’s default risk is.
Over the past 3 years it hasn’t mattered.
But that isn’t normal.
The Easy Money Phase is Over
For three years, AI was a one-way bet.
Buy anything connected to datacenter buildouts and watch it soar.
CoreWeave was the poster child - backed by Nvidia and OpenAI, the stock seemed bulletproof.
But the music stopped.
Now investors are waking up to what was always hiding beneath the surface.
What Comes Next
CoreWeave might survive.
That’s because the AI datacenter boom is real. Demand for compute isn’t going away.
But the days of buying on hype and headlines are over.
Now it’s about execution. Balance sheets. Cash flow.
And most importantly when looking at companies like CoreWeave: debt service.
CoreWeave has a $55.6 billion backlog and massive growth projections.
They also have billions in debt, idle GPUs bleeding interest costs, soaring CapEx and customers who can foreclose if things go wrong.
The easy money was made buying CoreWeave early and selling before anyone asked hard questions.
Now the hard questions are here.
And most investors holding the stock don’t even know what questions to ask.
Want help?
Equity Empire subscribers get my research and picks hand delivered to them. If doing all this research sounds hard - Equity Empire subscribers get picks sent directly to them - no research required. Just in the past year, our research got subscribers in early on names like Oracle (73% gain), Nebius (226% gain), Applied Optoelectronics (127% gain), Bloom Energy (92% gain), before they got the attention of “gurus”. When the YouTubers start talking about a stock … you’re in too late. CoreWeave, Oracle, and Nebius are a great example. If you get in early … and lock in gains - the drops are opportunities, not depressing.
Follow Me On X: https://x.com/InvestorVideos
Wow! Does nebius have anything similar to coreweave when it comes to SPV or alot of collateral?
How is it legal to create a office balance sheet entity and account the interests in the parent company's revenue?